Chase’s 5/24 rule: how to count yours, and when a card stops counting
Chase usually declines most of its cards for anyone who has opened five or more personal credit cards in 24 months, at any bank. How to count yours, and the date each card drops off.
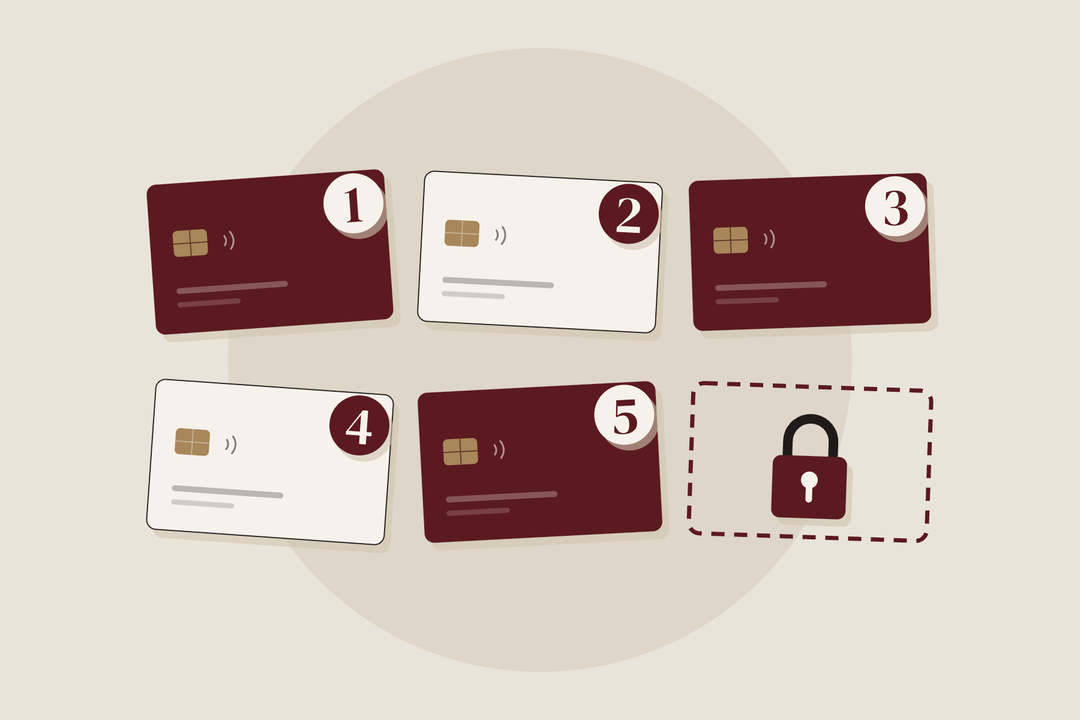
Chase usually declines most of its cards for anyone who has opened five or more personal credit cards in the last 24 months, at any bank. The rule isn’t in Chase’s terms, but years of applications show it. Here is what counts, what doesn’t, and the date each card drops off.
The rule
5/24 isn’t in any Chase card’s terms. What is known comes from years of applications reported by applicants, and from Chase’s denial letters, which are reported to cite too many accounts opened recently. Two things follow. The rule can change without notice, and an application at 5/24 usually fails no matter how strong the credit score or how long the relationship with Chase.
The count runs across every bank. Two Amex cards, two Citi cards and one Capital One card opened in the last two years put an applicant at 5/24 before a single Chase card is involved.
What counts and what doesn’t
The count is built from the personal credit report: new card accounts with an opening date inside the last 24 months.
Counts
- Personal cards from any bank, charge cards included.
- Closed cards, if they were opened in the window.
- Authorized-user cards, which usually appear on the report.
- Business cards that report to personal credit, such as most Capital One, Discover and TD business cards.
Doesn’t count
- Most business cards, including Chase Ink and those from Amex, Citi and Bank of America.
- Declined applications. Only accounts that were opened count.
- A credit check on its own. Hard inquiries aren’t accounts.
- Loans: car loans, mortgages and student loans.
Authorized-user cards are the common surprise. Being added to a partner’s or parent’s card can push the count to five.
When a card stops counting
Applications point to a monthly count: a card stops counting on the first day of the month after its second anniversary.
| Card opened | Turns two | Stops counting |
|---|---|---|
| March 15, 2024 | March 15, 2026 | April 1, 2026 |
| October 2, 2024 | October 2, 2026 | November 1, 2026 |
| December 31, 2024 | December 31, 2026 | January 1, 2027 |
The shortcut: in any month, count every card opened in that same month two years earlier, or later.
Count yours in two minutes
- Pull the reports. All three bureaus’ reports are free every week at AnnualCreditReport.com, the site set up under federal law. Any one of them works for the count.
- List the cards opened in the window, closed ones and authorized-user cards included. Four or fewer is under 5/24.
- Five or more? Find the fifth-newest card. The month after it turns two is the first month a Chase application has a real chance.
Chase business cards
The Ink cards sit on both sides of the rule. An applicant still needs to be under 5/24 to be approved for one, but once open, an Ink card doesn’t report to the personal credit report, so it doesn’t add to the count. An applicant at 3/24 who opens an Ink card is reported to stay at 3/24.
The order of applications
Because only Chase looks at the count, the order matters more than the number. While under 5/24, Chase cards go first: every card from another bank uses a slot that a Chase card needed. Ink cards can fit in between without using one.
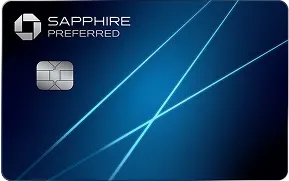
Chase Sapphire Preferred
The usual first Chase card: a low fee, and points that transfer to airlines and hotels.
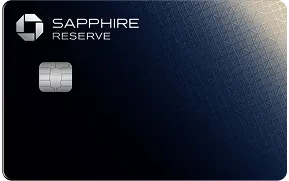
Chase Sapphire Reserve
The premium Sapphire, with Sapphire Lounge access. Its welcome bonus is judged separately from the Preferred’s.
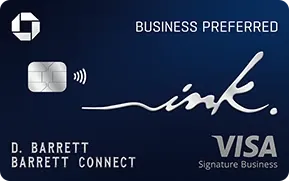
Chase Ink Business Preferred
A business card that needs an applicant under 5/24, but is reported not to add to the count once open.
“To approve” and “Adds to the count” follow reported applications, not Chase’s terms.
A separate rule for the Sapphire bonus
Being under 5/24 gets an application considered. Whether the welcome bonus pays is decided separately, and that rule is in Chase’s own terms:
“This credit card is unavailable to you if you currently have this card open. The new cardmember bonus may not be available to you if you previously held this card or received a new cardmember bonus for this card. We may also consider the number of cards you have opened and closed in determining your bonus eligibility.”
Each Sapphire card is judged on its own, so holding one doesn’t rule out the other’s bonus. Applicants report that Chase now shows a notice during the application when the bonus won’t be paid, before the application is submitted, so it can be stopped there.
The Atelier Take
Count from the credit report before any new card. Under 5/24, Chase cards go first, and Ink cards fit in between without using a slot. At five or more, the calendar decides when Chase is worth an application.
Each card’s earning, credits and fee are in the Sapphire Preferred, Sapphire Reserve and Ink Business Preferred reviews, or side by side in the card compare tool.
Card names and logos are trademarks of their owners, used only to identify their products. Points Atelier is not affiliated with or endorsed by them.